Square Suspend Verified Account After Full Documentation
A digital marketing firm provided all required identity and financial documents but still had its payments blocked by the payment processor.
By Simon Bennett ·
A small business that helps other companies with online marketing and search engine optimization did everything it could to follow the rules. The company, which operates entirely online, submitted every document required to verify its identity and financial standing. It provided a valid government issued ID. It linked a bank account that had already been verified through third party software. It submitted the Employer Identification Number document directly from the Internal Revenue Service. It produced the formation documents for its limited liability company. It even held a valid contract with a client for the full amount of money in dispute.
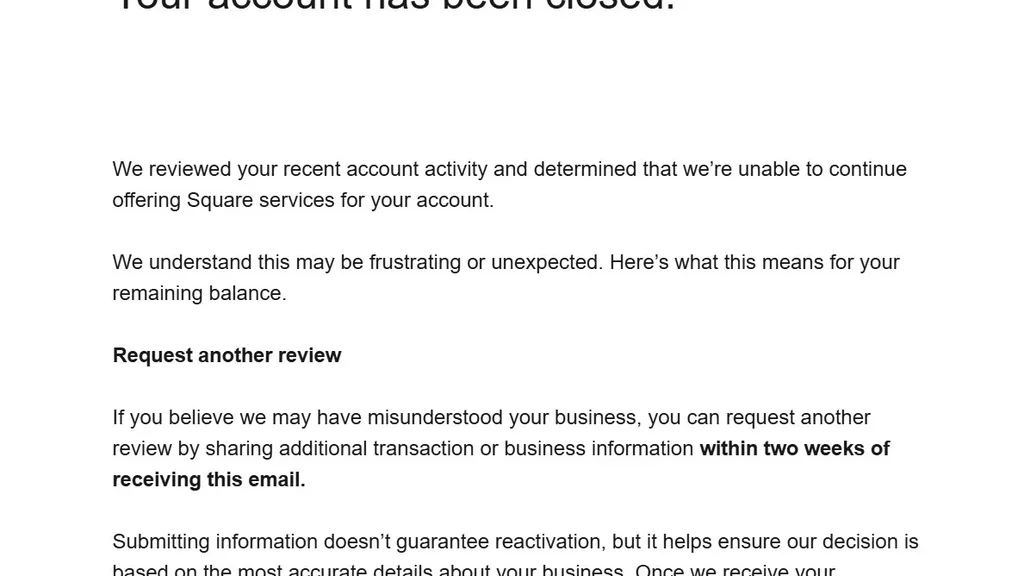
Despite this complete package of proof, Square suspended the account.
The suspension was not triggered by a missing document. It did not happen because the bank account failed a check. The IRS did not flag the tax ID as fake. Instead, Square applied a rule that was not even listed as a valid reason for suspension in their own guidelines. The business had not broken any rule. The rule itself seemed to not exist in the formal list of causes. But the automated system had made its decision, and the system does not accept questions or exceptions.
The business appealed the decision immediately. Square promised a response within ten days. It took two full weeks for an answer to arrive. When the response finally came, it was a denial. There was no explanation. There was no stated reason. There was no human being to call, no office to visit, and no face to look at while being told that the business and its funds were no longer welcome.
It was simply a denial from a machine.
The business had given the company its identity, its tax records, its bank details, and the contract proving the transaction was real. In return, it received a suspension with no cause and an appeal with no details. This situation highlights a specific part of the contract that should concern every small business owner who uses the platform. The terms are written in plain language on the company website.
Section 12 of the General Terms of Service states that Square may terminate the terms or suspend the account at any time for any reason. The phrase for any reason is key. It implies that a reason is not required. The company can suspend the account whenever it chooses, and the justification is optional.
Section 13, which deals with the effect of termination, adds that Square will not be liable for compensation, reimbursement, or damages for any termination or suspension of services. This means the company can take the account, hold the money, and disrupt the business operations without being held financially responsible for the loss.
The Payment Terms contain similar language. Section 12 says that Square may defer payout or restrict access to proceeds, either temporarily or indefinitely. This allows the company to hold the revenue that a client has already paid. The money sits in the company account while the system decides the fate of the merchant.
Section 14 of the Payment Terms discusses the reserve for holding funds. It states that Square may require a reserve for any reason related to the use of the services. The amount of this reserve is determined reasonably by us. The phrase reasonably determined by us stands out. It is not determined by a bank, a regulator, or a judge. It is determined by the company itself.
There is a notable contradiction in the contract. Section 1 of the Payment Terms begins with a clear statement that Square is not a bank. The company describes itself as a payment facilitator and a software platform. It acts as the pipe that moves money, not the reservoir that holds it. Yet, this software company has more power over a business account than the traditional bank that actually holds the funds. A bank must follow specific rules and explain its actions. A bank can be regulated. Square is a technology company with a suspension button that has no off switch.
The contract also limits how a business can fight back. Section 22 of the General Terms says that disputes must be handled through individual arbitration in Oakland, California. Class actions are not allowed, and there is no jury. Section 19 caps the total liability of the company at the fees it earned from the business in the three months before the issue occurred, or five hundred dollars, whichever is greater.
Five hundred dollars is the maximum value the contract assigns to the business in the event of a dispute. Section 7 goes further by stating that if there is a dispute about who owns the account, Square will be the sole arbiter. The decision will be final and binding on all parties. The company acts as the player, the referee, and the stadium in the same game.
This structure creates a system where a non bank company acts with the authority of a bank. An automation system scrutinizes the business with zero reason and zero explanation. A merchant who verified every step of the process is suspended by a rule that was not even a listed reason. The appeal process takes twice as long as promised and ends without a word.
The business cannot easily dispute the decision because doing so triggers arbitration in the company home city under company rules for a prize capped at five hundred dollars. Square even maintains a list of unsupported industries in its Payment Terms. Item six on that list is direct marketing or subscription offers or services. A marketing and SEO firm is very close to that category. The machine does not need the rule to be strictly true. It only needs the rule to be convenient.
Where is the bank that must explain itself? Where is the regulator that must show its work? Where is the human being who must look a customer in the eye and say that the account is suspended and here is why?
There is no one. There is a dashboard. There is a denial. There is a machine that has never met the business, never read the contract, and never spoken to the client. The machine has already decided.
This is not just a payment processor. It is a toll booth on the only road the business has. It is run by a company that is not a bank, governed by a contract that says it can do what it wants, when it wants, for any reason, and owes nothing for it.
The verified business did everything right. Square did not need it to. That is the whole story. That is the whole system. Until a company that is not a bank starts acting like one, every small business in the country is one algorithm away from losing its money, its account, and its voice. There is no reason given and no explanation owed.
The current system relies on the assumption that the merchant will accept the decision. The business provided its ID, its IRS EIN, its LLC formation documents, a verified bank account, and a signed client contract for the full sum. Square suspended the account anyway. It denied the appeal two weeks past its own deadline. It never once explained why.
The lack of transparency is the central issue. The company uses its position as a payment facilitator to hold power over merchants who depend on the flow of funds. The contract terms allow for indefinite holds on money and final decisions made by the company itself. The arbitration clause in Oakland adds a geographic and procedural hurdle for businesses that are not based in California.
The five hundred dollar liability cap is a significant barrier to seeking compensation. If the suspended account held thousands of dollars in client payments, the potential loss far exceeds the maximum payout under the contract. The business is left to choose between accepting the loss or paying for arbitration that may yield less than the cost of the dispute.
The list of unsupported industries adds another layer of risk. While the marketing firm was not explicitly on the list, its services were close enough to trigger the algorithmic review. The system does not require a perfect match to the list. It requires a pattern that fits its internal logic. The logic is not shared with the merchant.
The suspension happened after full verification. This means the initial checks passed. The ID was valid. The bank account was real. The tax ID was correct. The LLC documents were in order. The client contract was signed. None of this mattered to the suspension decision. The machine had already flagged the account for other reasons that were not disclosed.
The appeal process was the only chance for the business to get a human review. The promise of a ten day response became a two week wait. The denial arrived with no text explaining the specific trigger. The business was left to guess what went wrong. It could have been the industry type. It could have been the transaction volume. It could have been a random flag in the system. The company did not say.
More Business · Rip-Off Report · Report a business · Got a Story?